Homeowners should think carefully about potential loan costs before using their home equity. Around the end of the month, it’s wise to reassess your financial health. Entering September 2026, this evaluation becomes even more crucial. With inflation high, potential Federal Reserve rate hikes on the horizon, and household debt levels significant, your financial decisions now carry weight.
If you’re a homeowner, tapping into your home equity might be a sensible move. Home equity levels reached a record high in 2025. Interest rates on home equity loans remain more affordable compared to credit cards or personal loans. This makes borrowing from your home equity attractive as the fall months begin.
Home equity loans provide the advantage of a fixed interest rate, helping you budget with accuracy. Borrowers needing a larger sum, such as $50,000, find this particularly helpful. However, your home serves as collateral, so failing to repay risks foreclosure. It’s crucial to understand your commitments before applying, starting with knowing your monthly payments.
Monthly Costs for a $50,000 Home Equity Loan
The average home equity loan interest rate stands at 8.21% as of August 24, 2026. Consider these monthly payment examples based on typical repayment terms:
- 10-year loan at 8.21%: $612.20 per month
- 15-year loan at 8.21%: $483.91 per month
By comparison, here are historical costs:
January 2026 Rates:
- 10-year loan at 8.18%: $611.40 per month
- 15-year loan at 8.13%: $481.59 per month
September 2025 Rates:
- 10-year loan at 8.43%: $618.06 per month
- 15-year loan at 8.31%: $486.82 per month
Fall 2024 Rates:
- 10-year loan at 8.47%: $619.13 per month
- 15-year loan at 8.38%: $488.86 per month
Currently, rates and costs align with early 2026 but are lower than in previous years. Invest time in exploring lenders, and you might find competitive offers. Don’t delay too long, though. A Fed rate hike could prompt lenders to increase rates preemptively. Lock in a favorable rate now to avoid higher costs later.
In summary, a $50,000 home equity loan opened this September could yield monthly payments between $484 and $612, based on the repayment term. Evaluate your ability to handle these payments. If they seem burdensome, look for lower rates or consider alternatives like a Home Equity Line of Credit (HELOC) or reverse mortgage.
 Amazon Offers Discounts to Employees at Whole Foods
 Hidden Fees in Real Estate Transactions: A Growing Concern
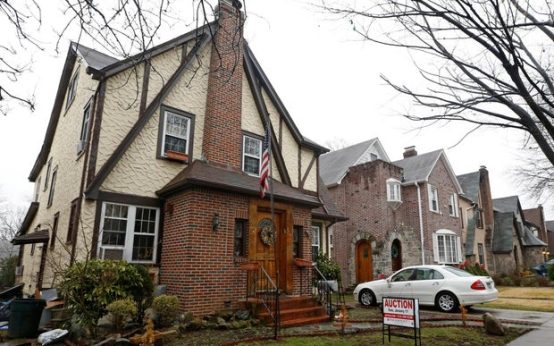 Trump’s Childhood Home Sells for Nearly $2 Million After Renovation
 Luxury Five-Bedroom Home with Rooftop Deck in Edgewater
 Trump’s Housing Affordability Agenda Faces Challenges
 Easing Mortgage Standards: A Complex Debate