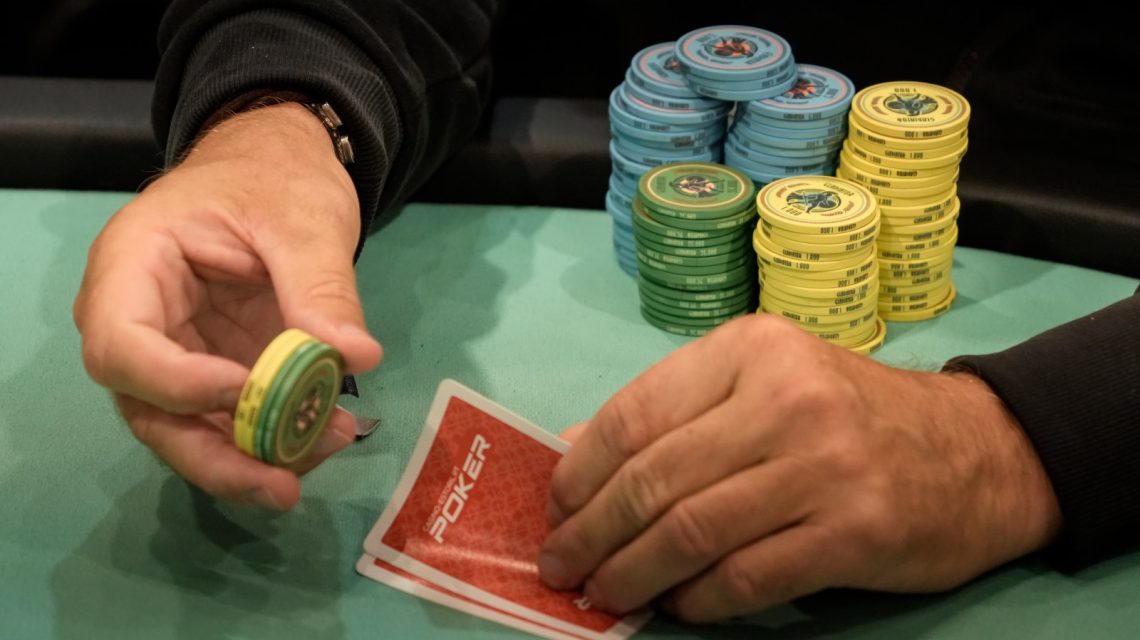
A rising number of Gen Z adults view sports betting as a form of investment, leading financial experts to caution that gambling profits do not enhance future Social Security benefits. A recent Betterment Retail Investor Survey conducted among 1,000 investors from March 27 to April 3, 2026, revealed that over half of the Gen Z participants (52%) used investment funds for sports betting at least once in the past year. Among these, 14% diverted their investments toward betting multiple times a month. Comparatively, 31% of millennials, 10% of Gen X, and 4% of baby boomers redirected investment dollars towards it at least once last year.
Even though successful bettors are required to pay taxes on winnings, these earnings do not typically count towards the earnings history used to calculate Social Security retirement benefits. Michael Ryan, a finance expert and the founder of MichaelRyanMoney.com, expressed concerns to Newsweek, stating, “What worries me is what the betting money replaced. If it was money that would have gone into a Roth IRA, 401(k), brokerage account, or even an emergency fund, the loss isn’t just today’s bet. It’s potentially 30 or 40 years of compounding that never happens.”
This trend emerges amidst an already uncertain retirement outlook for younger Americans. Social Security benefits rely heavily on a worker’s lifetime earnings record. Individuals whose years of income come from non-covered earnings activities risk facing reduced retirement benefits.
The Rise of Online Sports Betting
Gen Z has increasingly embraced online sports betting following its legalization across the United States. Alex Beene, a financial literacy instructor at the University of Tennessee at Martin, told Newsweek, “Dollars not invested in your twenties don’t just disappear today. They could lose 40 or 50 years of potential growth, and research is already connecting expanded online betting with lower investment and greater debt.”
The IRS mandates that recreational gamblers report winnings as taxable income, including sports-betting gains; however, the SSA tracks different earnings categories. Social Security benefits are founded on covered wages from employment and net earnings from self-employment subject to payroll taxes. Winnings from recreational gambling do not typically fall under these categories. Consequently, a gambler may owe federal income taxes on substantial jackpots without benefitting from any boost to their Social Security earnings record.
“Sports betting itself isn’t going to bankrupt Social Security, but gambling winnings generally don’t build a worker’s Social Security earnings record, and a generation entering retirement with inadequate private savings would become even more dependent on a program already facing serious funding challenges,” Beene remarked.
Understanding $100,000 in Winnings
If someone earns $100,000 through sports betting within a year, none of this income contributes to their Social Security retirement benefits. In contrast, a $100,000 salary from a conventional job would factor into Social Security’s benefit calculations. Social Security bases benefits on a worker’s 35 highest years of covered earnings. An additional earning year of $100,000 could increase retirement benefits by around $36 to $76 per month, depending on the earnings history.
This can significantly impact Gen Z. Kevin Thompson, CEO of 9i Capital Group and host of the 9innings podcast, shared with Newsweek, “Gen Z is truly at an impasse. They are dealing with structural unemployment and a high cost of living, which leads them and others to seek fast gains and take on higher risks. The main downside for Gen Z is potentially having less Social Security income to rely on. Many already feel Social Security won’t be there for them by the time they retire, so the mentality becomes: Why bother?”
Sports Betting as a Professional Career
There is an exception for professional gamblers. Those who qualify can report gambling activity as self-employment income. The IRS allows professional gamblers operating as a trade or business to file Schedule C, and the SSA may recognize these earnings as self-employment income subject to Social Security taxes. Hence, gambling income might generate Social Security credits and future retirement benefits. Qualification depends on the frequency of betting and record-keeping practices.
Thompson noted, “If Gen Z truly believes Social Security won’t be around in the future, you may see more people start businesses and use structures that combine W-2 wages with business distributions.”
Financial advisors consistently stress that Social Security was structured around traditional employment and payroll tax contributions. Although sports betting might occasionally provide a financial windfall, it does not substitute the steady covered earnings essential for building retirement security.
The Path Ahead for Gen Z
With sports betting gaining mainstream acceptance, retirement experts are focusing on how younger Americans manage and perceive money. For now, Gen Z workers should understand that although a sizable sports bet win might boost their bank balance today, it is unlikely to increase their future Social Security checks.
Ryan emphasized, “Social Security was never supposed to do the whole job. If younger people reach retirement with less private savings because gambling got mentally filed under ‘investing,’ Social Security doesn’t get weaker. They become more dependent on it.”
 Northwestern Opens New Ryan Field with Stunning Victory
 Jack Murphy’s Impactful Return Powers Lincoln-Way East to Victory
 San Francisco 49ers Begin Strong NFL Season Amid Owner’s Suspension
 Quentin Burrell’s Journey at Mount Carmel
 Sheriff Ron Hain Retires from Kane County
 Cubs Face Challenges and Opportunities After Disappointing Season